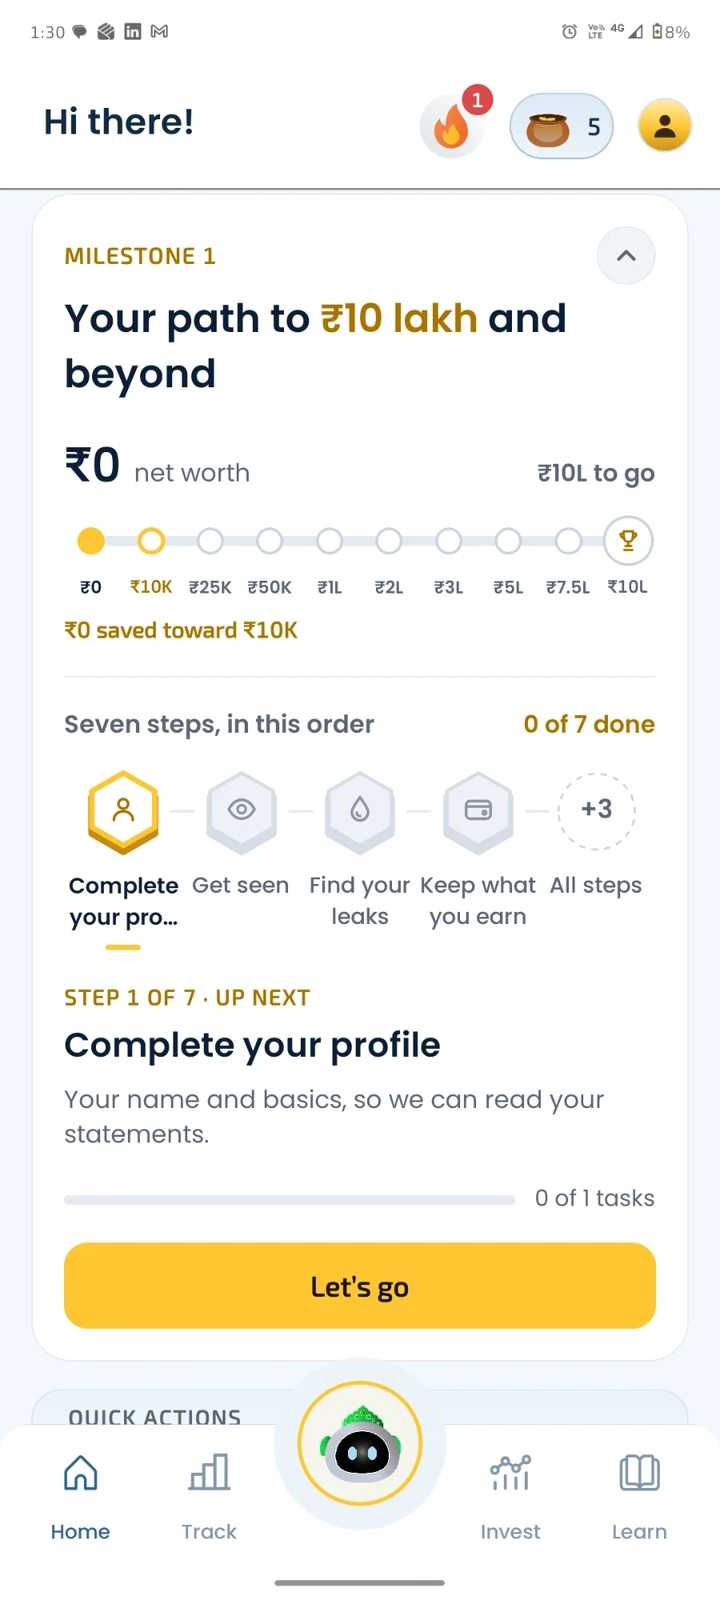
Your path

Yourpathtofirst₹10 lakhandbeyond.

Step by step, with long-term investing and no shortcuts.

₹10 lakh is a milestone most first-jobbers can reach with discipline. It is the slowest ten you will ever make. Everything after it is structurally easier.

Get it onPlay Store Download on theApp Store
Kuber.AI Home with stacked insight cards
₹InsightnowSitting idle: ₹18,000
Back-up money2mDays covered: 41
KSalary landed. Want to move ₹9,000 to your SIP tomorrow?
₹
Illustration only
Step 1 of 6 · See where it goes₹10L+
Six steps

Six steps, in this order.

Track · October ₹38,400 spent
Rent₹15,000
Food & orders₹9,200
Travel₹5,400
Shopping₹5,100
Subscriptions₹3,700
₹Sitting idle in savings₹62,000
Bank SMSGmailRead-only
Back-up money
57%of your number
Your back-up number₹2,10,000
Kept aside₹1,20,000
Gap flagged · ₹90,000 to go
Insurance check 2 gaps found in your cover
Term coverNot added
Bought young, it costs less for the whole term.
Health coverEmployer only
₹3 lakh from your employer. It ends with the job.
Own health coverGap flagged
Cover beyond your employer's, in your name.
Leaks · this month
Music app · unused₹199
OTT plan · unused₹499
Card late fee₹750
Back every month₹1,448
Credit score762
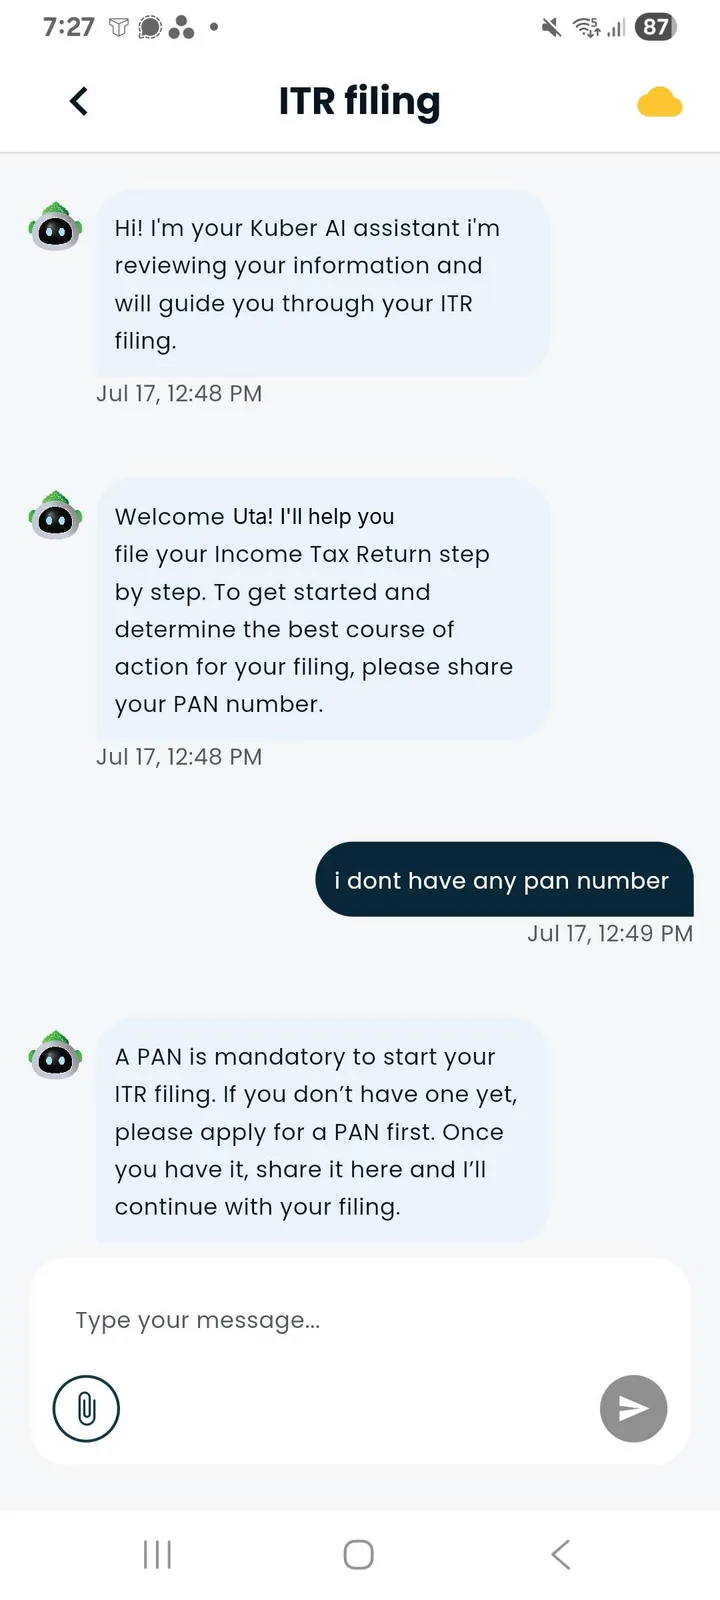
ITR filing chat SIP set-up
Illustration only

Six steps, in this order.

01 / 06
₹₹10 lakh and beyond
01

See where it goes

Spends, net worth and what is sitting idle, every month. Link bank SMS or Gmail, upload a statement, or add it yourself; read-only, revoke anytime.

How the app helps · Track shows it all on one screen. Nothing moves without you.

EXAMPLE · ILLUSTRATION ONLY ₹38,400 spent in October ₹62,000 sitting idle in savings.
02

Back-up money

3 months of income or 6 months of expenses, whichever is higher, kept safe and reachable.

How the app helps · The app shows your back-up number and flags the gap.

EXAMPLE · ILLUSTRATION ONLY Back-up number: ₹2,10,000 6 × ₹35,000 expenses beats 3 × ₹60,000 income. Gap: ₹90,000.
03

Get insured

Term cover bought young, and your own health cover beyond your employer's. Insurance is protection, not an investment.

How the app helps · The insurance check flags the gap.

EXAMPLE · ILLUSTRATION ONLY Employer health cover: ₹3 lakh It ends with the job. Own cover: gap flagged.
04

Fix the leaks

Cards paid in full, forgotten subscriptions, late fees, and a 750+ credit score before you need it.

How the app helps · The Leaks view and credit score show what moved it. The money you could be investing and are not.

EXAMPLE · ILLUSTRATION ONLY ₹1,448 a month back Two forgotten subscriptions (₹698) and one ₹750 late fee.
05

Keep more of it

EPF match, corporate NPS, the right tax regime, and filing ITR even at nil tax.

How the app helps · ITR agent and old-vs-new regime in the app, with TaxBuddy as our tech and ERI partner.

File your ITR →
EXAMPLE · ILLUSTRATION ONLY New regime: ₹9,600 less tax Compared side by side before you file.
06

Invest every month

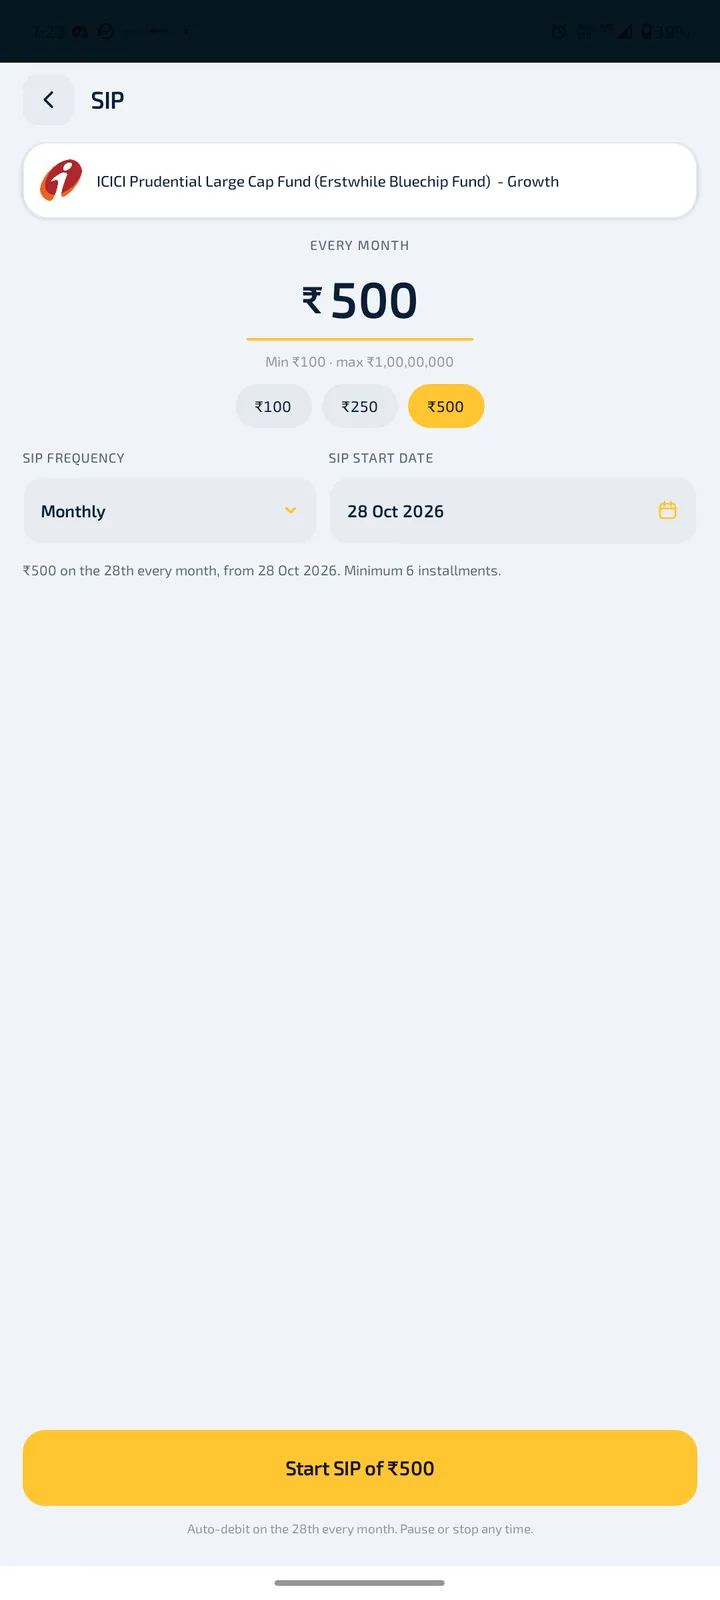
A SIP on salary day + 1, a step-up every appraisal, direct plans where available, digital gold SIP from ₹10, and the funds and stocks you already hold, linked. Coffee-can patience.

How the app helps · Set up a SIP or gold SIP in a few taps.

EXAMPLE · ILLUSTRATION ONLY ₹9,000 SIP on the 2nd Plus ₹500 a month in digital gold.
Mutual funds distributed by Simplify Money Private Limited, ARN-363095. Gold offered through SafeGold. Digital gold is not regulated by SEBI. Mutual fund investments are subject to market risks. Read all scheme-related documents carefully.
The scoreboard

Your path to first ₹10 lakh and beyond

₹1,80,000 invested so far · illustration only
The ladderSo farIf you keep goingWhat you put in
₹10K₹50K₹1L₹2.5L · next₹5L₹10L ★₹25L₹50L₹1Cr ₹50K₹2.5L₹50L You are here · ₹1.8L Time →
Invested so far₹1,80,000
Rungs climbed3 of 9
Next rung₹2.5L
Milestone₹10 lakh
Illustration only: a steady ₹9,000 monthly SIP at an assumed 11% a year. Returns are not assured, and markets do not move in a straight line.
The ladderSo farIf you keep goingWhat you put in
₹10K₹50K₹1L₹2.5L · next₹5L₹10L ★₹25L₹50L₹1Cr You are here · ₹1.8L Time →
Invested so far₹1,80,000
Rungs climbed3 of 9
Next rung₹2.5L
Milestone₹10 lakh
Illustration only: a steady ₹9,000 monthly SIP at an assumed 11% a year. Returns are not assured, and markets do not move in a straight line.

How far is ₹10 lakh?

₹ / month
₹1,000₹50,000
Saving it as-is, no returns9 years 4 months
Invested · assumed 10–12% a year6 yrs 3 mo – 6 yrs 7 mo
Illustration only; returns are not assured.

Three ways to get there faster

01 Fix the leaks What you stop losing goes into the SIP.
02 Step up the SIP Raise it every appraisal, before lifestyle catches up.
03 Count what you already hold EPF, funds and stocks you own move you up rungs.
Kuber.AI

Kuber.AI keeps you on track.

Check-ins and answers in your language
Progress against your next rung
Streaks and badges in Learn
Regulatory status SEBISEBI Registered Investment Adviser · Reg. No. INA000023728
Kuber.AI chat
Kitna bacha is mahine?
₹14,200 so far. Next rung is ₹2.5L.
Getting started

What happens after you sign up

1
Your number and one OTPThat is the whole sign-up.
2
Tell Kuber.AI when salary landsGet your 50/30/20 split and how far ₹10 lakh is.
3
Count what you already haveConnect, upload or add it manually. Read-only.
4
Start a SIP, buy gold or file taxesAsk Kuber.AI along the way.
We read only what you link, upload or add, and only to show it back to you. We never move money without you, and never sell your data.
FAQ

Questions people ask

Start with the basics in order: see where your money goes, keep back-up money aside, get term and health cover, and fix leaks like late fees and unused subscriptions. Then invest a fixed amount every month, ideally the day after salary lands, and raise it every time your salary rises. The order matters more than the product: each step protects the next one.

It depends on how much you put in each month and what markets do. At ₹9,000 a month, saving alone takes 9 years 4 months. Investing can shorten that, but returns are never fixed; the calculator above shows an illustrative range at an assumed 10–12% a year, and stepping up your SIP each year moves it further.

No. Market-linked investments can go down as well as up, and returns are not assured. What you control is how much you invest, how regularly, and for how long. The figures on this page are illustrations only, not a forecast or a promise.

A simple way to split take-home pay: 50% for needs like rent, bills and EMIs, 30% for wants like eating out and travel, and 20% for saving and investing. It is a starting point, not a law; if rent is high in your city, the split will shift. Kuber.AI works out your split from when your salary lands and shows where you stand.

Keep 3 months of income or 6 months of expenses, whichever is higher. Hold it somewhere safe that you can reach within a day or two, such as a savings account or a sweep-in fixed deposit, not in equity. It is the money that stops a job change or a hospital bill from becoming debt.

They do different jobs, and you usually need both. Term insurance protects the people who depend on your income; investing grows your money over time. Insurance is protection, not an investment, so avoid plans that mix the two. Buying term cover young keeps the premium lower for the whole term.

Start with an amount you can keep up after needs and back-up money, even if it is small. Set the SIP for the day after salary day so it goes out before spending starts, and step it up every appraisal. Consistency over many years matters more than the starting amount.

Download The App Today

Let's achieve financial goals together with Simplify Money App

Play Store App Store
QR code to download Simplify MoneyOr scan with your
phone camera
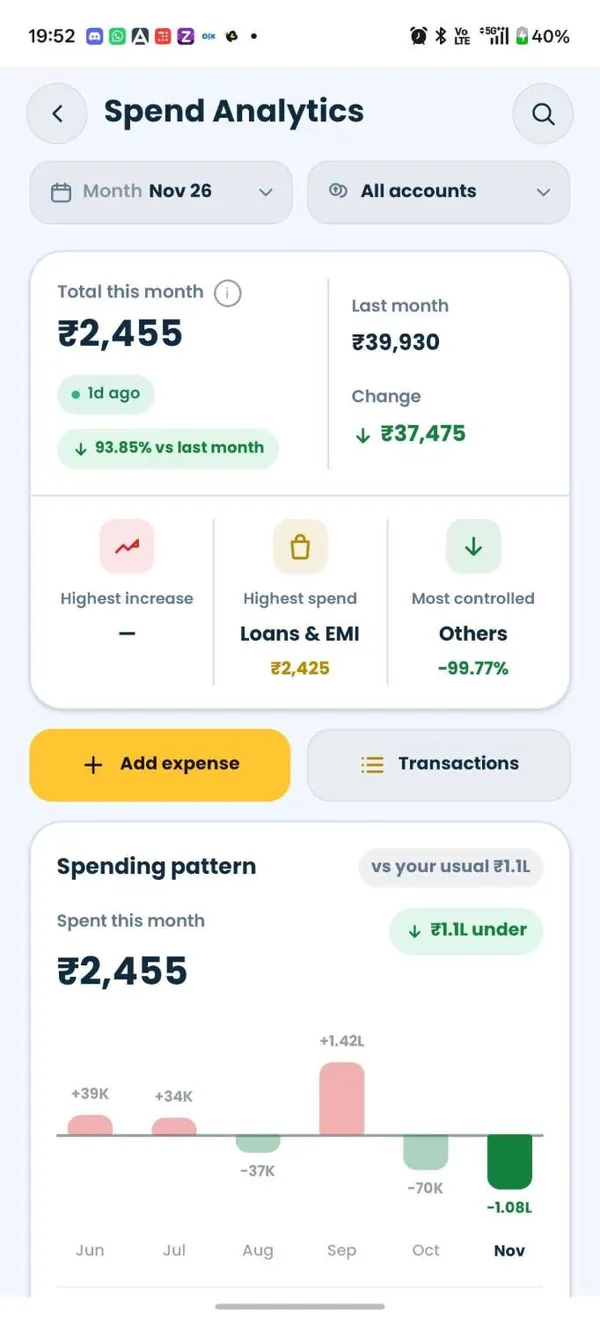
Spend analytics
Milestone 1: your path to first ₹10 lakh
Kuber.AI chat
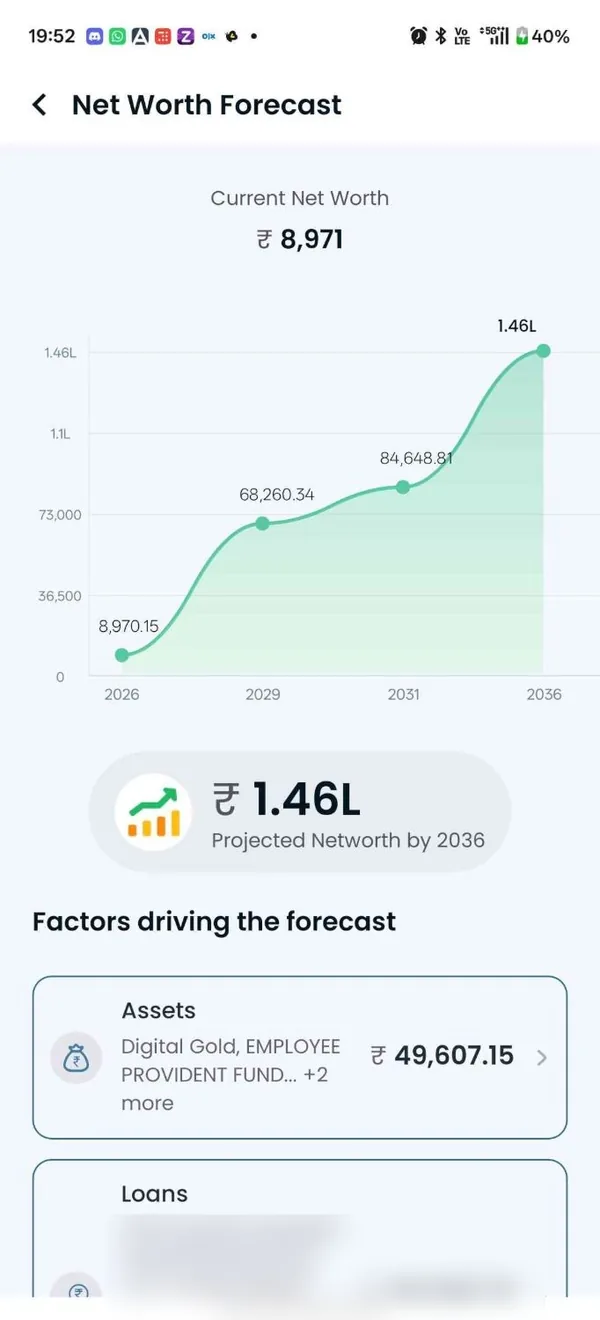
Net worth forecast
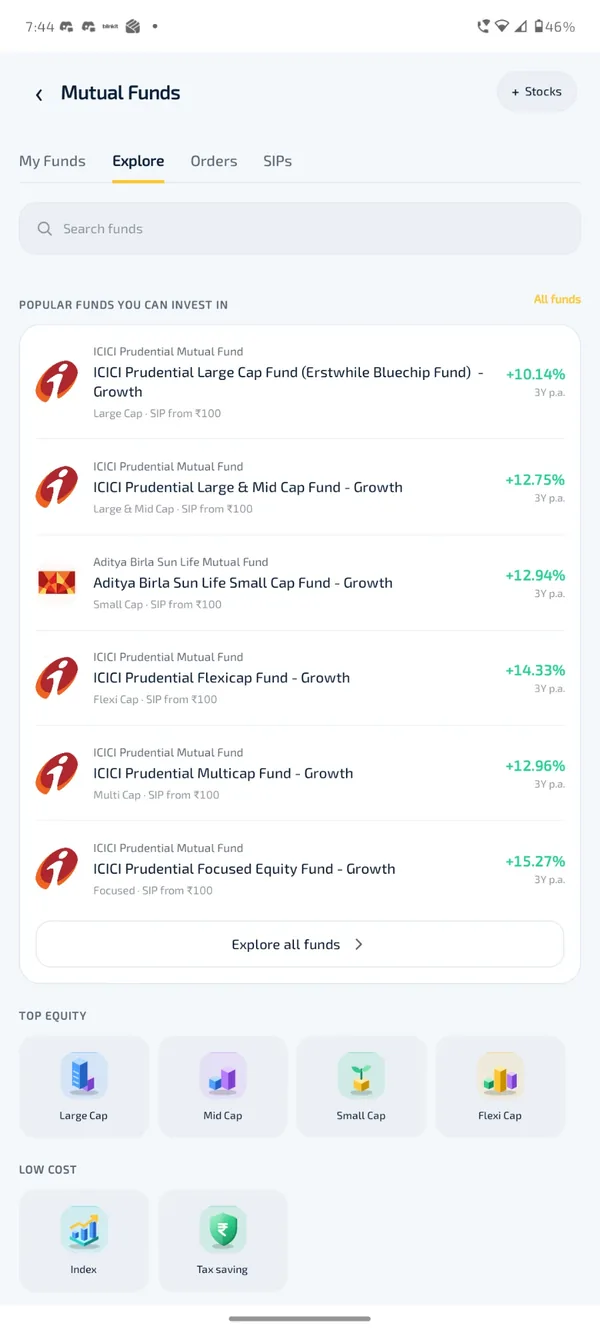
Mutual funds